Soft Saving: Why 73% of Gen Z Prioritize Today Over Retirement
73% of US Gen Z say today's quality of life beats retirement savings, per Intuit. Meet Soft Saving—frugality that doesn't sacrifice you—seen through Japan's saving traditions.
 By Marcus BennettPhotographer / US Trends, English Edition Editor·2026.07.10 published·2026.09.06 updated·8 min read·2 sources
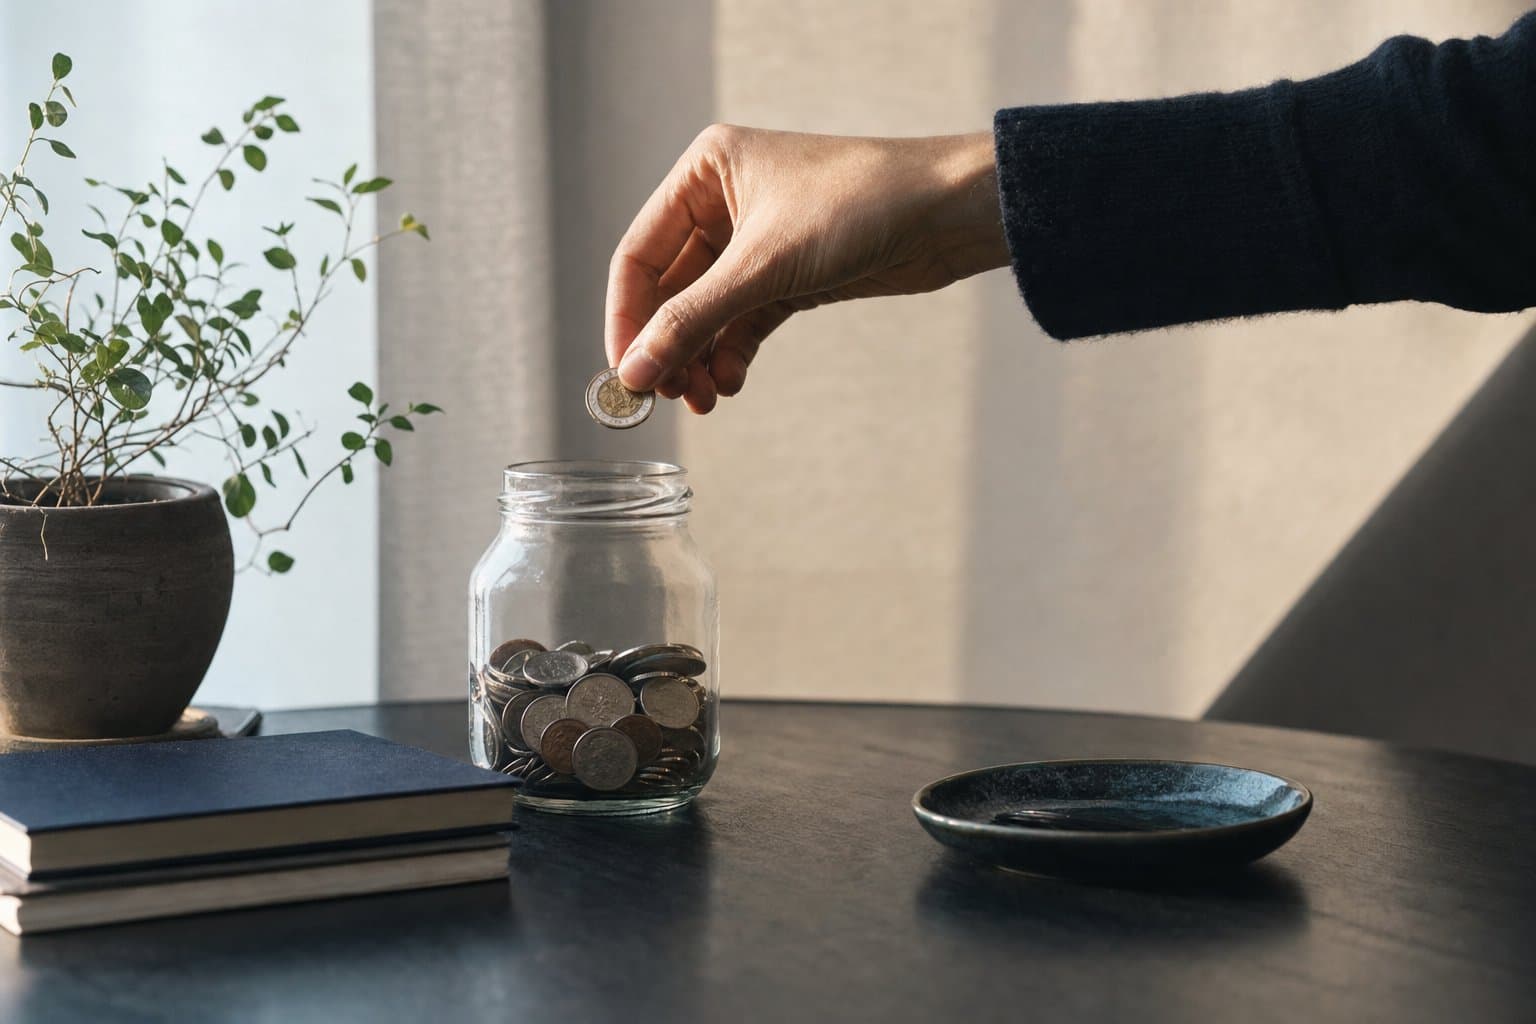
Sacrifice now, for the sake of the future. For a long time, that was the right answer when it came to saving—giving up what you wanted, turning down invitations, postponing joy, stacking it all up for future security. But younger generations overseas have begun quietly saying no to that sacrifice-first money mindset.
What is spreading is Soft Saving: frugality that refuses to sacrifice your present quality of life or your mental health. Instead, you save gently, within a comfortable range, and keep it up for the long run. The key point is that Soft Saving is not a declaration that you have stopped saving. It is a reordering of priorities: the state of being able to keep saving matters more than the speed at which you save.
If Loud Budgeting—declaring your frugality proudly—is the loud approach, Soft Saving is the gentle habit. For anyone who has felt worn down every time they moved money into savings, or who has watched a strict budget snap back into a spending binge, it offers another option. In this article we will work through the definition of the term, how it differs from what people now call hard saving, and how to translate it into a routine that fits daily life in Japan.
What is Soft Saving? Soft vs hard saving, defined
Soft Saving is a way of relating to money in which saving for retirement or the distant future is no longer the top priority. Instead, you keep saving gently, within a range that protects your present quality of life and your mental breathing room. Target amounts stop being sacred, and the act of continuing becomes the achievement itself.
That is the core of the definition. Its counterpart is what people now call hard saving: the traditional, willpower-dependent approach of setting a fixed quota and blaming yourself when you miss it. The difference between the two is not the amount saved—it is what happens in the month that does not go to plan.
The shift shows clearly in the data. A survey by accounting-software giant Intuit found that 73% of US Gen Z prioritize today's quality of life over saving for retirement. Among Millennials the figure is 66%—nearly the reverse of Baby Boomers (31%). The grit-your-teeth-and-save model no longer fits how younger generations feel.
The term Soft Saving itself spread from around 2023, largely on US TikTok, and that same year CNBC covered the trend as a reshaping of the personal finance goals held by Gen Z and Millennials. The drivers are universal: inflation and rising prices, which make cutting back feel like it barely moves the needle; an open-ended anxiety about the future; and burnout from the pressure to always keep pushing. In that climate, doubt about wearing down today's happiness for money's sake is quietly spreading.
In Japan, by contrast, the concept name remains almost unknown. The practice, however, is not. The habit of accumulating small amounts steadily, and the instinct that dislikes waste without tipping into harsh self-denial, are both already part of daily life here. For readers in Japan this is less an imported new idea than a familiar approach finally being given a name.
Why it works: saving stress and Japan's tsumitate
Soft Saving works not because it is a comforting attitude but because it intervenes in the mechanism that makes saving collapse. The typical failure loop goes like this: you set an ambitious quota; you hit it for a few months; an unexpected expense or plain exhaustion breaks the streak; you conclude that you are simply someone who cannot save; you stop tracking altogether; and then the rebound spending arrives. What drives that loop is not the amount—it is guilt.
Guilt rarely improves behavior; it makes you look away from the thing that produces it. That is the feeling of no longer opening the budgeting app, of not checking the account balance. Soft Saving removes the self-punishment step from the design. If a zero-yen month counts as expected rather than as failure, you can come back the following month.
Raise the continuation rate and time starts doing the work, even when each contribution is small. Let us clear up a common misunderstanding. Soft Saving is not the claim that you should stop saving, or that the future does not matter as long as today is fun. It argues close to the opposite: something small that never stops leaves you with more than an ambitious plan you abandon after a few months.
It does not dismiss preparing for the future—it rebuilds that preparation into a form you can actually sustain. The same logic explains why it resonates in Japan. Japan has a long tradition of tsumitate—small, painless, consistent contributions accumulated over time. Layered on top is mottainai, a balanced value that warns against waste without tipping into extreme self-denial.
Japanese people were practicing soft saving in daily life long before it had a label. Seen from that angle, saving usually becomes stressful here at the moment you start measuring yourself against someone else's benchmark—average household savings by income bracket, or what people your age are said to hold. Soft Saving returns the measuring stick to your own life.
One caveat: if money anxiety is severe enough to affect your sleep or your health, that is a matter for a public advice service or a qualified professional, not a budgeting tweak. Results and the right approach vary from person to person.
How to start Soft Saving: 3 steps, no quota
Here is a three-step Soft Saving you can start today. First, give yourself permission to set no fixed target. Drop rigid quotas like save 30,000 yen a month and make zero this month is fine a genuine option. The trick is not to grant that permission only in your head—write down somewhere, in a note or a calendar, that zero months are part of the plan.
When a zero month actually arrives, the written record lets you file it as expected rather than as failure. Cutting off the fuel for guilt is the first step to lasting. Second, prefer save what is left over save first. Rather than carving into your life to save up front, set a comfortable small automatic contribution (even a few hundred yen) and top it up only in the months you can.
A useful gauge for the amount: it should be small enough that you do not have to change any behavior when it leaves your account. The moment you have to skip seeing friends to cover it, the setting is too high. Conversely, if you have topped it up easily for 3 months running, you can nudge the baseline up a little.
There is no universally correct answer to how much you should save—it moves with income, household, and fixed costs. When the sums involved are large enough to worry you, talk to a qualified financial professional. Third, once a month, review the emotions of your money; 10 minutes is enough. Instead of staring only at numbers in a budget, write down one purchase you were satisfied with and one you regretted.
After 3 months you will start to see your own satisfaction pattern. This is not managing figures—it is learning what spending actually makes you happy. Decide in advance how to diagnose trouble, too. If you have avoided looking at your balance for 2 months straight, the amount is too heavy: halve the automatic contribution.
If the balance is growing but the anxiety has not eased, the cause may not be the amount at all but an unclear picture of the years ahead—in that case leave the contribution alone and list out your fixed costs instead. The stopping point should be explicit as well: if saving starts eating into your sleep, your meals, or your relationships, you have hit the ceiling. The key is never to weigh saving against your mental health. When it gets hard, ease off. If it is still going, that alone is a win.
The takeaway: choose saving that lasts
What Soft Saving teaches is that you are allowed to step off the belief that if I cannot save, I am a failure. Money is a tool for enriching your present life—not a punishment that demands you surrender today for the sake of tomorrow. When saving has become a source of stress, the problem is usually not weak willpower but a plan that was too heavy to carry.
Lowering the setting is not defeat; it is the adjustment that keeps the habit alive. Loud Budgeting, declared loudly, and Soft Saving, continued gently, are not opposites; they combine. Decline boldly, save comfortably—find the balance that fits you. For now, reset your savings quota to zero this month and keep only the smallest habit you can sustain.
The amount does not matter. A version of you still doing the same thing next month is worth more than the balance itself. That is the kind of frugality that carries you the furthest. If you want to go deeper into the philosophy behind Soft Saving, Bill Perkins's Die With Zero is the definitive read (link at the end of this article). (Our free AI budgeting template, the Digital Kakeibo we use ourselves, is also available from Editor's Tools.)
FAQ
What does Soft Saving actually mean?
It means not treating saving for the distant future as your top priority, and instead saving gently within a range that protects your present quality of life and mental health. Continuing matters more than hitting a target. The term spread on US social media from around 2023. It is not a declaration that you have stopped saving—it is a reordering, where the state of being able to keep going outranks the speed at which you save.
How is Soft Saving different from hard saving?
The difference is not the amount but how you treat a month that misses. Hard saving sets a fixed quota and leans on willpower, so falling short turns into self-blame. Soft Saving treats a zero month as expected, which makes it easy to return the next month. Each contribution may be smaller, but the continuation rate tends to be higher. Which suits you depends on your temperament and how stable your income is.
Saving money is stressing me out. What should I do?
Start by checking whether your contribution is small enough that you do not change any behavior when it leaves your account. If covering it means skipping time with friends, it is too high. If you have avoided checking your balance for 2 months running, halve it. If the anxiety persists—especially if it affects your sleep or your health—that is beyond a budgeting tweak, and it is worth talking to a public advice service or a qualified professional.
Can you really build savings without any sacrifice?
Outcomes vary from person to person, and no approach can be guaranteed. As a principle, though, something small that never stops lets time work for you more than an ambitious quota you abandon after a few months. Soft Saving is not about skipping preparation for the future; it rebuilds that preparation into a sustainable form. How much you actually need depends on income and fixed costs, so take larger decisions to a qualified financial professional.
How much should I be saving each month?
There is no single right answer. A workable gauge is an amount small enough that nothing about your daily behavior has to change when it leaves your account—starting from a few hundred yen is fine. If you have topped it up comfortably for 3 months running, nudge the baseline up; if it starts to bite, bring it down. Comparing yourself to averages is where this usually turns painful, so keep the measuring stick inside your own life.
Does being unable to save mean I lack discipline?
More often than not the problem is a plan that was too heavy, not weak willpower. Ambitious quotas tend to break within a few months, and once they break, guilt makes people stop looking at their finances entirely—which is exactly when rebound spending happens. Lowering the setting is not defeat; it is the adjustment that keeps the habit alive. Simply redesigning so that a zero month counts as expected changes how easily you come back.
About this article
This article was written by Marcus Bennett (Photographer / US Trends, English Edition Editor) of the Tokyo Decoded editorial team, with sources and facts checked by the team. We keep editorial independence from advertisers. See our editorial policy.
Sources
Related
Loud Budgeting: The US Trend Changing How We Talk About Money
Loud Budgeting has topped 140M views on TikTok. The new flex is saying 'I'm saving' out loud. Here's the data behind it—and how to practice it from Japan.
Read more →
The 2026 Guide to Global Money Trends: From Loud Budgeting to Cash Stuffing
Loud Budgeting, Soft Saving, Cash Stuffing — a single map of the money trends born overseas. Which one fits you, and how to actually practice it in Japan.
Read more →
What Is Moneymaxxing? Optimizing Options, Not Just Balances
Moneymaxxing isn't about growing the number. It's about widening the options your existing money can buy.
Read more →